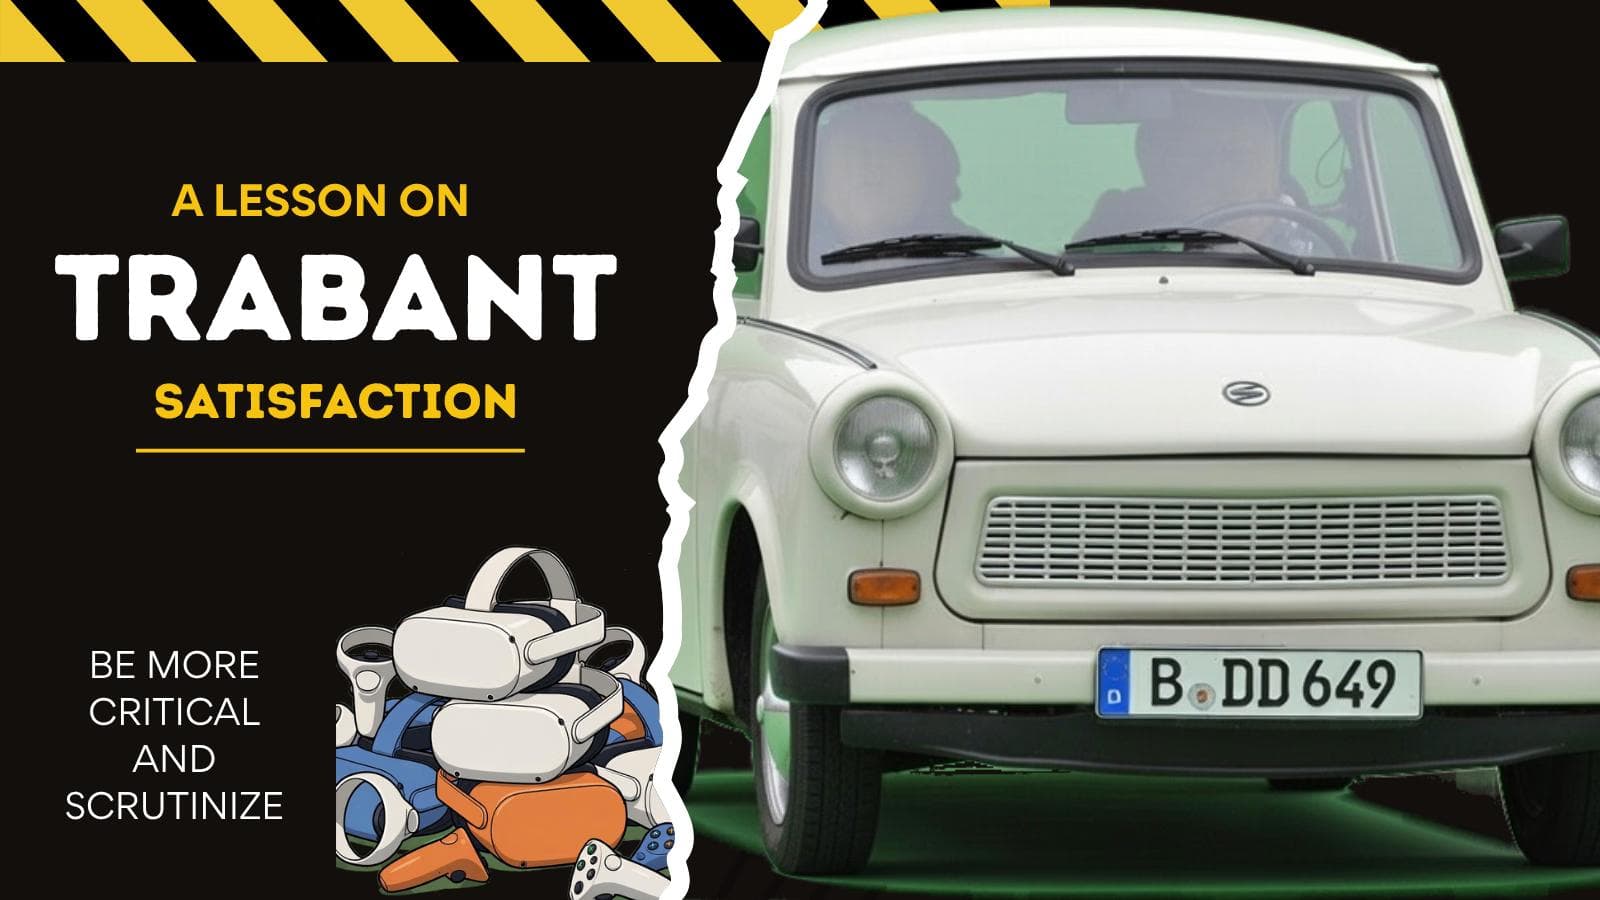
Surely that indicates tremendous customer satisfaction. Except it doesn’t.
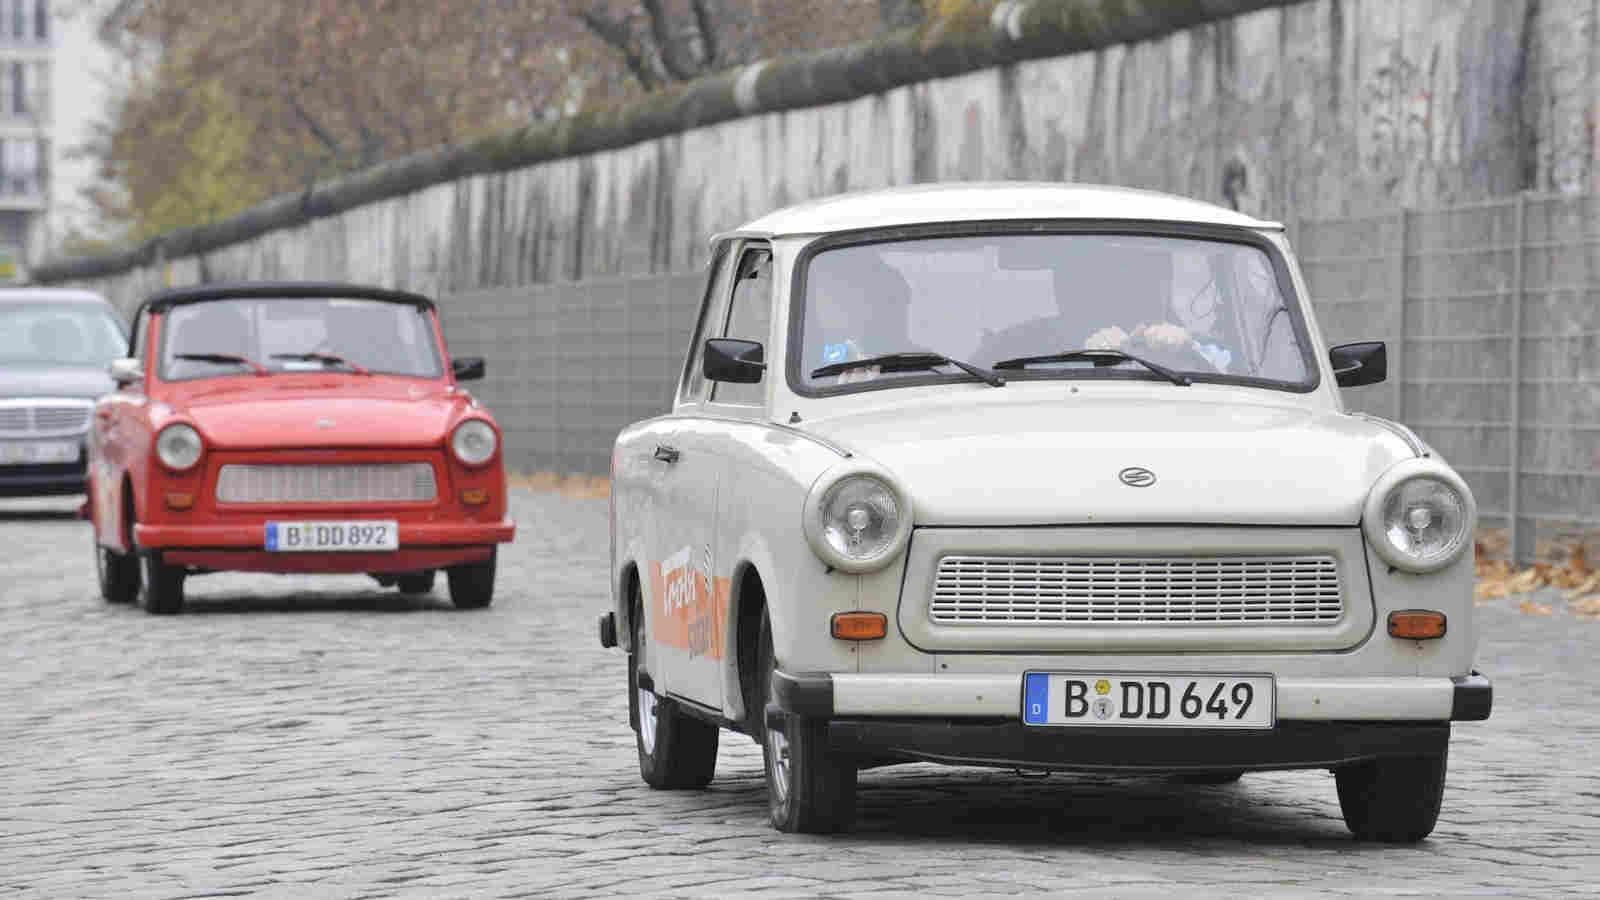
The Trabant existed in a market where choice was severely limited. There were few alternatives, supply was restricted, and consumers accepted compromises because having a car was considerably better than not having one.
That does not mean nobody liked their Trabant. Many people undoubtedly did. It became part of family life, created memories, and today even has a devoted enthusiast community.
But its sales figures cannot be interpreted in the same way we would interpret millions of purchases made in a highly competitive market.
People bought what was available.
And when East Germans suddenly gained access to a much wider range of Western products, consumer preferences changed extraordinarily quickly.
There is an important lesson in that.
Sales do not automatically equal preference. Market share does not automatically equal satisfaction.
Choosing Something and Accepting Something Are Not the Same
We make this mistake surprisingly often in technology.
Company A has 70% of a market. Therefore, customers must prefer Company A. Maybe. But there are plenty of other explanations.
Perhaps Company A got there first. Perhaps it has the strongest distribution. Perhaps developers build primarily for its platform. Perhaps buyers already have compatible software. Perhaps procurement departments recognize the brand. Perhaps competitors disappeared.
Or perhaps there simply isn't a genuinely different alternative.
There is an enormous difference between:
“This is what I want.”
and:
“This is the best thing available to me.”
Sales figures struggle to distinguish between the two.
That matters particularly in emerging technology markets because a dominant product can gradually define our expectations of the entire category.
We stop asking whether something needs to work that way.
We simply assume that is what the technology is.
And VR may have fallen into exactly that trap.
Have We Confused VR With the Products Selling VR?
For much of the past decade, the most visible VR systems have developed around a relatively similar philosophy.
Gaming is important. 6 DoF is expected. Hand controllers and tracking are expected. Cameras are expected. Movement is expected. Accounts, connectivity, software updates and larger platform ecosystems are increasingly normal.
There is nothing inherently wrong with any of these things. For the applications that require them, they can be excellent. But schools purchasing these systems does not necessarily prove that schools wanted all of those things.
Sometimes schools simply wanted VR.
- They wanted students to visit somewhere they could not physically go.
- They wanted to visualize something that was difficult to understand on a flat screen.
- They wanted students to practice language, examine scientific concepts, experience environments, explore careers, rehearse decisions or concentrate on something without the distractions surrounding them.
So they bought what was available. Then, frequently, the school adapted itself to the technology.
- Teachers learned setup procedures.
- IT departments absorbed additional management.
- Schools dealt with accounts and updates.
- Rooms were cleared because students needed space to move.
- Students required greater supervision because movement created additional risk.
- Management systems were purchased because devices and content needed managing.
And eventually all of this became so familiar that we started calling it simply “VR implementation.”
But perhaps some of it was never an inherent requirement of VR. Perhaps it was a requirement of the particular VR systems available to us.
That distinction is important.
Because the fact that customers are willing to work around a product does not necessarily mean they are satisfied with its design. Sometimes it simply means they want the outcome badly enough to tolerate the process.
We may be mistaking accommodation for preference.
What Happens When Something Genuinely Different Appears?
This is where the Trabant analogy becomes useful. The interesting question is not whether people bought and used the product. Obviously, they did.
The interesting question is what happens once customers are given a genuinely different choice. For education, imagine a VR system where:
- setup is minimal;
- movement is optional rather than assumed;
- internet connectivity is unnecessary for normal use;
- student accounts are unnecessary;
- privacy is designed into the architecture;
- operating costs are predictable;
- the hardware is expected to remain useful for years;
- there is plenty of ready-made content;
- schools can create their own content;
- and the least technical teacher in the school can pick up the headset and use it.
Would some schools choose that instead? We don't really know.
Because education has had remarkably few opportunities to make that comparison. And that brings us to something happening in the VR market right now.
VR Headset Sales Are Falling
Global VR headset shipments have been declining.
Counterpoint Research reported a 12% year-over-year fall in global VR headset shipments during 2024. In the first half of 2025, shipments fell another 14% year over year.
More recently, Counterpoint data reported that global VR headset shipments fell 18% year over year in Q2 2026, as well as 16% compared with the preceding quarter.
Those are significant numbers. It is tempting to look at them and conclude:
- People are losing interest in VR.
- Perhaps they are.
- That explanation should certainly remain on the table.
- But it is not the only explanation.
- Because a falling market tells us what people are buying.
- It does not necessarily tell us why they are not buying.
Maybe People Aren’t Rejecting VR
What, exactly, is declining? Interest in virtual experiences? Interest in immersive learning? Interest in simulation? Interest in being transported somewhere else?
Or interest in the particular combination of price, weight, content, complexity, platform, accounts, tracking, controllers and use cases currently packaged together and sold as VR?
Those are very different things. Maybe people really have decided that VR isn't particularly useful. But maybe they are tired of the current proposition.
- Maybe the headsets are still too bulky.
- Maybe the price is too high.
- Maybe consumers do not see enough compelling new content.
- Maybe businesses want longer hardware cycles.
- Maybe schools do not want consumer gaming ecosystems.
- Maybe institutions want less complexity rather than greater capability.
Maybe customers have been asking a very simple question:
“Why do I need all of this just to do the thing I actually want to do?”
There is another interesting clue.
While conventional VR headset shipments have been declining, the wider market for technology worn on the face certainly has not disappeared.
IDC reported strong growth in the broader XR glasses-and-headsets category during Q2 2026. But only around 15% of those shipments were conventional headsets. The overwhelming majority were increasingly lighter glasses-based devices.
Consumers have not suddenly rejected the idea of wearable computing. The form they want may simply be changing. Perhaps the same possibility deserves consideration within VR.
Maybe VR Has a Solutions Problem
For education especially, this may be the more interesting question.
Not:
“Is VR dying?”
But:
“Is the version of VR we have spent the past decade selling reaching its natural limits?”
There is an enormous difference.
The next successful education VR system might not succeed because it does more. It might succeed because it asks schools to tolerate less.
- Less setup.
- Less supervision.
- Less unnecessary movement.
- Less data collection.
- Less dependence on networks.
- Less technical knowledge.
- Less operating cost.
- Less disruption to a normal classroom.
That does not mean sophisticated 6 DoF systems disappear. Quite the opposite. Where learners need to physically manipulate something, practice a motor skill, rehearse surgery, welding, assembly or another genuinely psychomotor task, those capabilities can be enormously valuable.
Use the right tool for the right job.
But perhaps we made a mistake when one particular type of tool came to represent the entire medium.
A decline in current VR headset sales therefore deserves attention. But it should also provoke curiosity. Because declining sales do not necessarily tell us that people have rejected the underlying idea.
- Sometimes customers enthusiastically choose a product.
- Sometimes they accept it.
- Sometimes they build procedures around it.
- Sometimes they tolerate its weaknesses because the benefit is still worthwhile.
- And sometimes there is simply one game in town, so that is the game everybody plays.
The truly interesting moment comes when someone offers a different game.
Only then do we discover how much of the old market represented genuine loyalty — and how much represented compromise.
Perhaps people are not becoming dissatisfied with VR.
Perhaps they are becoming dissatisfied with what we have decided VR has to be.
Sources
- Sensible-VR — “When Sales Don’t Mean Satisfaction / The Trabant Lesson.” The original concept document behind this article, including the distinction between product adoption and customer satisfaction and the idea that teachers, IT teams and classrooms may be accommodating systems rather than actively preferring their design.
- Deutsche Welle — “Trabant: The East German car remains iconic.” Notes that there was very little alternative to the Trabant in East Germany, demand exceeded supply, roughly three million were produced, and the cars rapidly disappeared from German roads once broader alternatives became available. (DW)
- Deutsche Welle — “Der Trabi wird 60.” Reports an average waiting period of roughly 12 years and describes the rapid shift toward more modern Western automobiles following German reunification. (DW)
- Counterpoint Research — “Global VR Market Declines 12% YoY in 2024; ‘AR+AI’ Smart Glasses to Take Centre Stage in 2025.” Reports a 12% year-over-year decline in global VR headset shipments in 2024, the third consecutive annual decline, while noting comparatively resilient enterprise demand. (Counterpoint Research)
- Counterpoint Research — “Global VR Headset Shipments Fall 14% YoY in H1 2025.” Reports a further 14% year-over-year decline during the first half of 2025. (Counterpoint Research)
- Counterpoint Research / Q2 2026 Global XR tracking. Counterpoint's September 2026 tracker covers shipments through Q2 2026; reporting based on the tracker states that global VR headset shipments declined 18% year over year and 16% quarter over quarter during Q2. (Counterpoint Research)
- IDC — Worldwide Quarterly Wearable Device Tracker / Augmented and Virtual Reality Headset Tracker, Q2 2026. Reports 35.3% year-over-year growth across the broader XR headsets-and-glasses market, while conventional headsets represented only 15.4% of shipments; audio glasses accounted for 70.3% and display glasses another 14.3%. (idc.com)